Quantitative Researcher · JPMorgan

Arghya Ghosh

I develop quantitative frameworks for financial markets, built on measure-theoretic probability and stochastic calculus. I apply them to the pricing, valuation, risk measurement, and stress testing of complex financial products, and to machine-learning models for algorithmic trading.

Mumbai, India

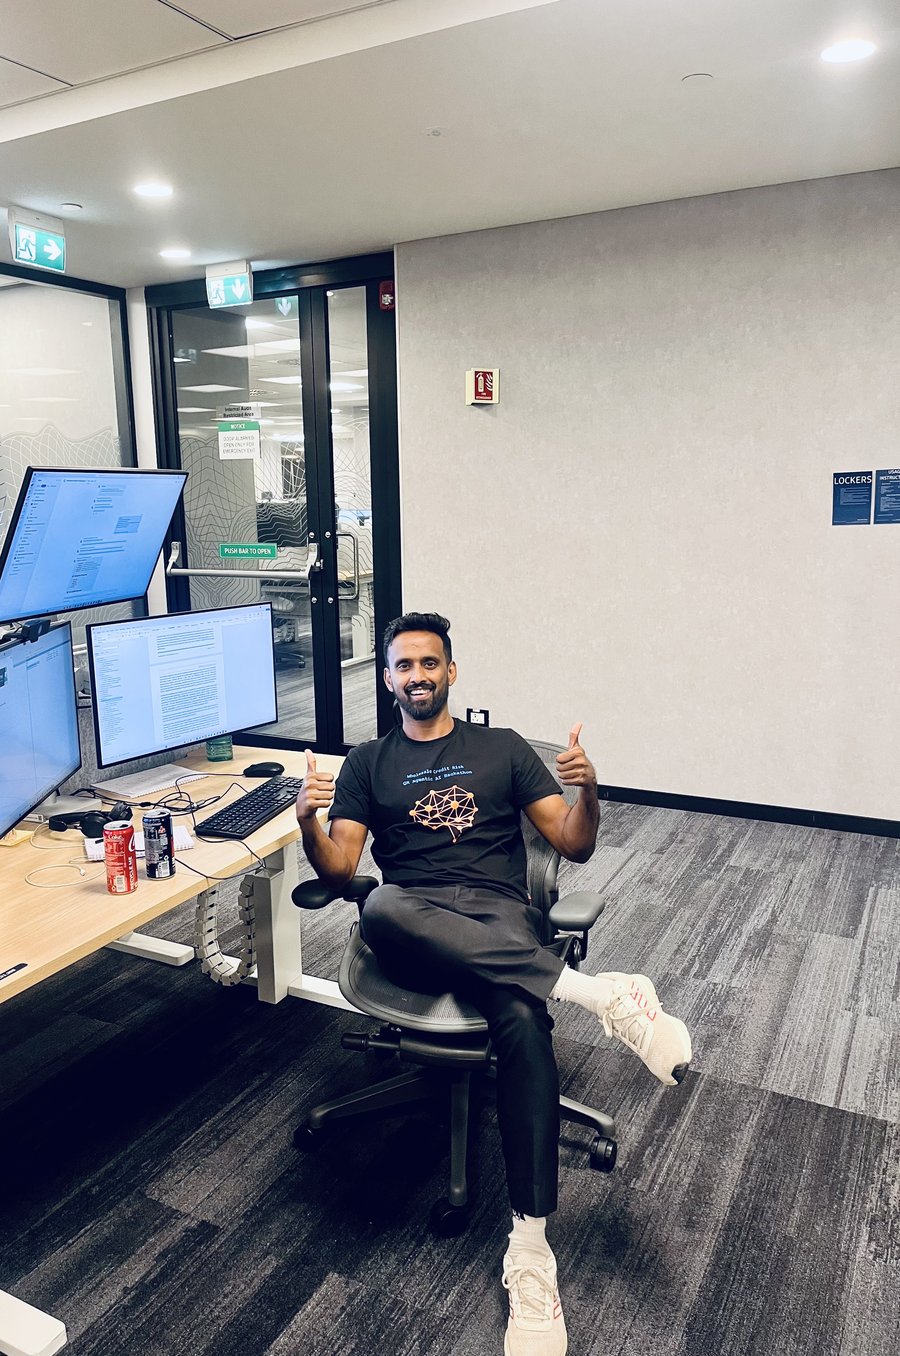
Arghya Ghosh at his desk, giving a thumbs up.

About

I'm a quantitative researcher at JPMorgan Chase, with over a decade developing, validating, and stress-testing stochastic and statistical models for complex financial systems — derivative pricing, securitized-product valuation, and the risk frameworks behind regulatory stress testing. My mathematical grounding is in measure-theoretic probability, stochastic calculus, and stochastic processes, and I care about models that are interpretable and theoretically grounded while remaining deployable at scale.

My independent research sits at the intersection of stochastic modelling, market-regime dynamics, and robust optimisation under model uncertainty. A large part of it is machine learning for algorithmic trading — deep and reinforcement-learning agents for portfolio allocation, regime-conditioned ensembles of QUBO, hierarchical-risk-parity and CVaR sleeves, and hedged multi-asset pipelines backtested on NSE equities. Alongside this I work on quantum and quantum-inspired methods for portfolio construction and credit-portfolio loss computation.

Professional & Research Experience

Vice President, Quantitative Research — JPMorgan Chase & Co.

August 2021 – Present
  • Lead end-to-end development of stochastic pricing and risk models for CRE, CMBS, and structured products used in regulatory stress testing (CCAR, CECL) and internal risk frameworks.
  • Built option-adjusted spread (OAS) and cashflow-waterfall / tranche pricing models for CMBS securitized products, translating collateral-level cashflow and prepayment dynamics into structural tranche valuations.
  • Designed the model-monitoring, back-testing, and obligor / collateral grading frameworks across the CRE, CMBS, and SPG domains, including performance thresholds and escalation triggers.
  • Built climate risk models integrating physical, transition, and market risk channels across 10,000+ collateral records; proposed a novel NOI volatility framework using a two-barrier Merton-type model.
  • Developed a scalable Python computational pipeline for the CRE Loss Engine, cutting runtime by ~35% and enabling cross-portfolio experimentation.
  • Member of the Quantum-Inspired Algorithm (QIA) working group of the JPMorgan Quantitative Research team.

Senior Associate, Model Risk Management — Morgan Stanley

October 2019 – August 2021
  • Validated AIRB / IRB, CCAR, and CECL credit risk models for large-scale portfolios, including residential mortgage, CRE, and structured products.
  • Created a benchmark model using fractional Brownian motion to capture the loss impact where independent-increment assumptions were failing.
  • Led performance monitoring, backtesting, and challenger-model development; automated validation workflows and analytical tooling to improve reproducibility.

Associate, Model Risk Management — Credit Suisse

July 2016 – October 2019
  • Validated stress-testing and scenario-generation models (Brownian Bridge frameworks, PPNR) and market risk models (IRC, VaR, expected shortfall).
  • Independently re-implemented and benchmarked derivative pricing models — credit derivatives (CDS, synthetic CDO / index tranches) and equity derivatives (vanilla and exotic options, structured notes) — against desk valuations.
  • Applied explainable ML techniques to improve transparency in complex forecasting and credit risk models.

Statistical Programmer — inVentiv Health

April 2011 – March 2012
  • Constructed clinical-trial datasets integrating longitudinal patient indicators and treatment histories; performed exploratory and inferential analyses supporting regulatory submissions.

Assistant System Engineer — Tata Consultancy Services

May 2010 – April 2011
  • Developed automation and configuration-management tooling and Unix-based scripting workflows to improve operational reliability of enterprise systems.

Research

My current focus is an independent research project, Kelly-type portfolio optimisation for pension-fund welfare under mean-reversion uncertainty, regime collapse, and downside constraints — a unified robust Kelly framework for long-horizon allocation when a predictive state variable may stop mean-reverting and a hard welfare floor must hold. Work in progress.

Alongside it: a methodology note from my model-risk work — a variance-adjusted monitoring band for LGD model performance — an implementation study adapting deep time-inconsistent portfolio optimisation (D-TIPO) to NSE equities, and a regime-conditioned hybrid allocation framework that switches between QUBO, HRP, and CVaR sleeves on a hidden-Markov market-regime signal.

Read about the research →

Publications

Quantum Amplitude Estimation for Expected Loss Computation under a Discretized Latent-Factor Model

Sole-authored · SSRN, January 2026. Presented as my final project for the Quantum Computing certification at IIT Delhi.

A quantum algorithm for credit-portfolio expected-loss estimation using a discretized latent-factor model. Loss functions are embedded via controlled rotations and evaluated with Grover-based amplitude amplification, giving a quadratic speedup over classical Monte Carlo.

A Unified Risk-Neutral Stochastic Simulation Framework for Securities-Backed (Lombard) Lending

With Dr. Ramesh Bhavisetti · International Journal for Multidisciplinary Research, Vol. 8, Issue 1 (Feb 2026).

A risk-neutral stochastic framework for the market–credit interaction in securities-backed lending. Structural wrong-way risk is modeled via an LTV-dependent Cox default intensity, with recovery and LGD endogenized through collateral dynamics and liquidation haircuts.

Structured lending · WWR

Projects

ALGO LAB — Quantitative Portfolio Management Platform · 2025

An institutional-grade quantitative portfolio pipeline for NSE-listed equities and ETFs, built from scratch and deployed as a live web application. A four-step pipeline — Universe Screener → Parameter Tuning → Walk-Forward OOS Backtest → Final Portfolio Weights — runs over ~115 instruments across 11 asset classes.

  • Portfolio construction via QUBO (quantum-inspired combinatorial optimization with simulated annealing + Max-Sharpe MVO), Hierarchical Risk Parity, and Robust CVaR with an ellipsoidal robustness penalty.
  • Ledoit-Wolf covariance shrinkage and James-Stein mean shrinkage to stabilize parameter estimates on limited history.
  • Walk-forward backtesting engine with configurable train / validation / test splits, plus Beta-Neutral, Drawdown-Triggered, and Put-Protection hedge overlays.

Education

Quantum Computing Certification — Indian Institute of Technology (IIT) Delhi

June 2025 – February 2026

Quantum mechanics for computing · qubit systems and quantum gates · quantum algorithms (Grover, phase estimation, amplitude estimation) · quantum machine learning · variational algorithms (VQE, QAOA) · Qiskit.

Final project: Quantum Amplitude Estimation for Expected Loss Computation under a Discretized Latent-Factor Model (SSRN, 2026).

M.Sc. in Applied Mathematics — Chennai Mathematical Institute (CMI)

July 2014 – April 2016

Measure theory · real analysis · topology · probability theory · stochastic processes · stochastic calculus · time series analysis.

Bachelor of Engineering — National Institute of Technology (NIT)

July 2006 – April 2010

Engineering mathematics · numerical methods · control systems · fluid mechanics · thermodynamics · strength of materials.
Research & Technical Skills

Mathematical & statistical foundations Stochastic calculus · probability & measure theory · time series analysis · econometrics · optimization · numerical methods · Monte Carlo simulation
Modeling & machine learning Statistical learning · forecasting models · PD / LGD modeling · cashflow modeling · scenario design · explainable ML (SHAP, LIME)
Quantitative finance & risk Derivative pricing (IR, FX, credit, equity) · OAS & tranche valuation · market, credit & liquidity risk · CCAR & CECL stress testing · structured products · CRE / CMBS modeling
Programming & scientific computing Python · R · MATLAB · SAS · SQL · VBA
Emerging domains Climate & ESG risk modeling · quantum computing

Talks

Contact

Best reached by email at arghya.ghosh130@gmail.com. A full CV is available as a PDF.